Office Report: Loan Maturities Add to Market Strain
Nearly $289.2 billion in office loans have recently matured or will mature by the end of 2028, according to Yardi Matrix information.
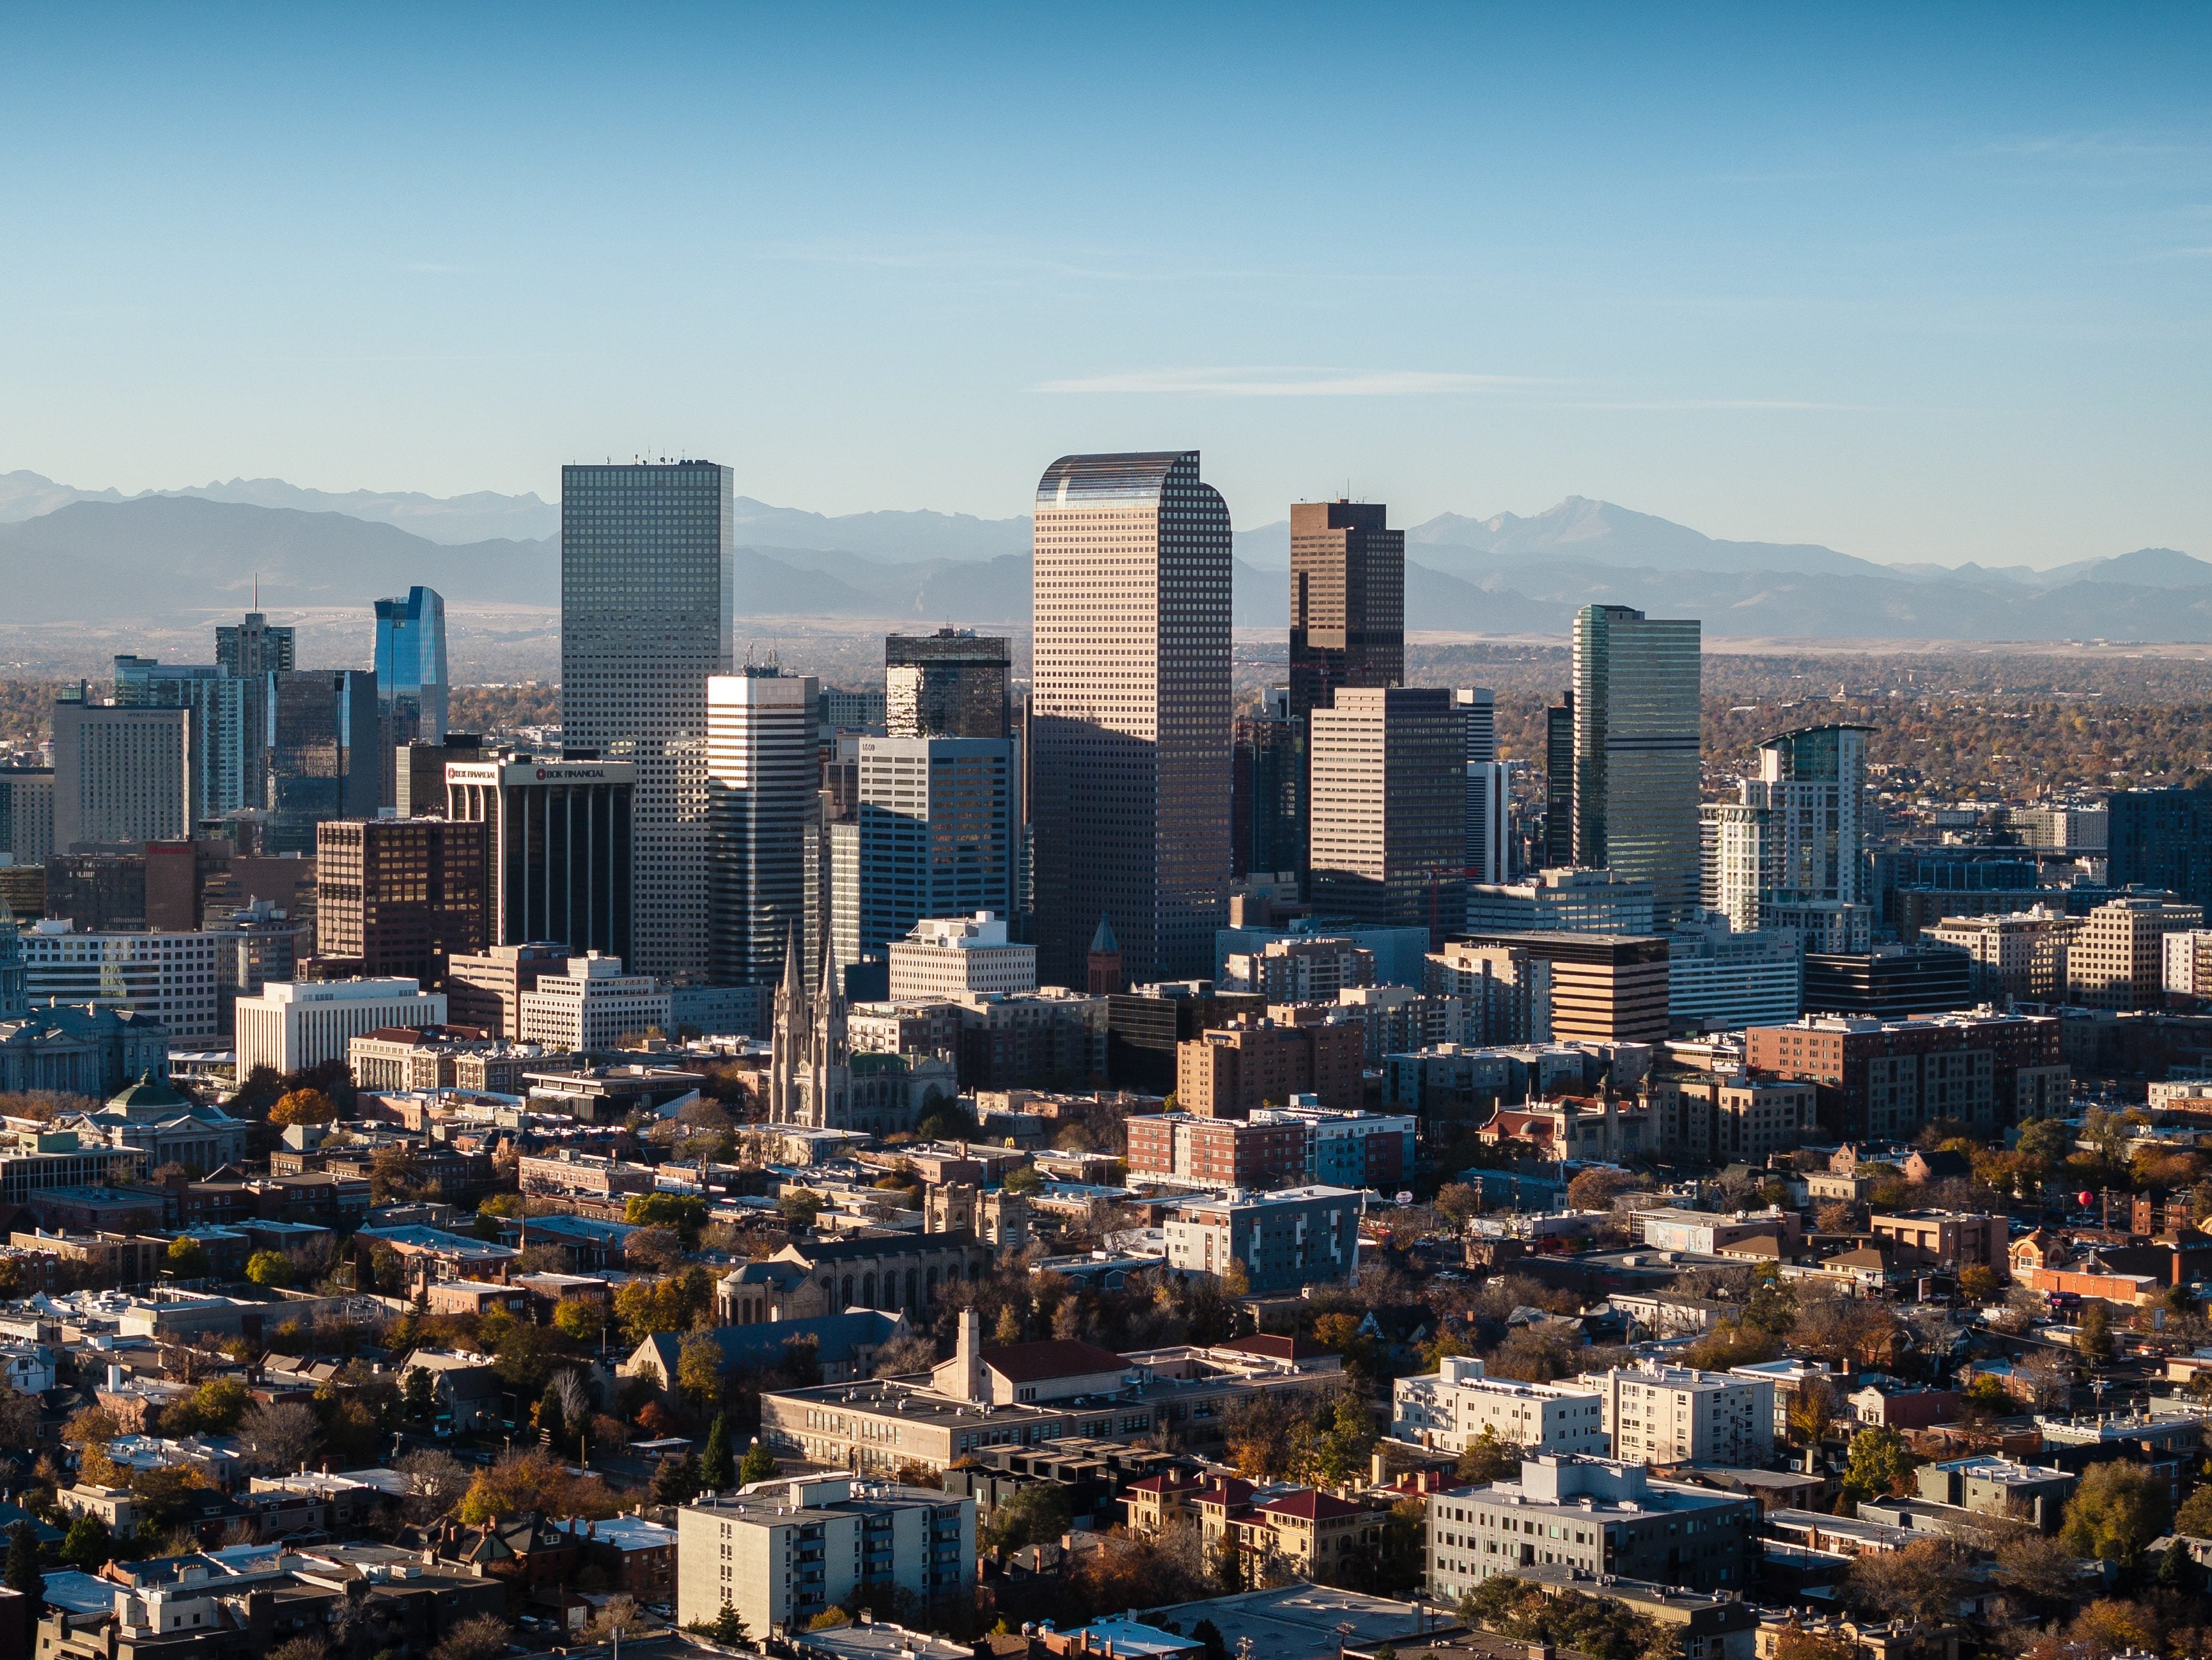
The U.S. office sector is facing another challenge as loan maturities are expected to peak over the next few years, adding distress to a market divided by shifting demand and divergent property performance, the latest Yardi Matrix national office report shows.
About 14,000 office properties carry loans that have recently matured or are scheduled to mature by the end of 2028. Those loans total $289.2 billion, accounting for 33.5 percent of all office loan volume. Lenders originated 58.8 percent of them before 2021, when expectations for office demand were more favorable.
Of those maturing loans, some 58.8 percent originated before 2021, when the sector was supported by stronger demand. Pressure is now building as those loans come due in a market reshaped by mass adoption of hybrid work and weak office attendance. The national vacancy rate stood at 17.8 percent in August, while office-using employment declined 0.2 percent year-over-year. Meanwhile, physical office occupancy averaged roughly 55 percent over the past few years, according to Kastle’s Back to Work Barometer.
READ ALSO: Office-to-Campus Conversions Open a New Path for Obsolete Buildings
While some markets have recovered much of their pre-pandemic demand, eight of the top 25 office metros still record vacancy rates above 20 percent. These markets account for $61.6 billion in maturing loans—or 7.1 percent of the total office loan volume.
Seattle is a market on that list, facing an elevated maturity risk as 70.1 percent of its $8.3 billion in maturing loan volume issued before 2021, while it had a 24.7 percent vacancy rate in August. Other high-vacancy markets facing significant maturity volume include the Bay Area ($13.5 billion) and San Francisco ($12.6 billion).
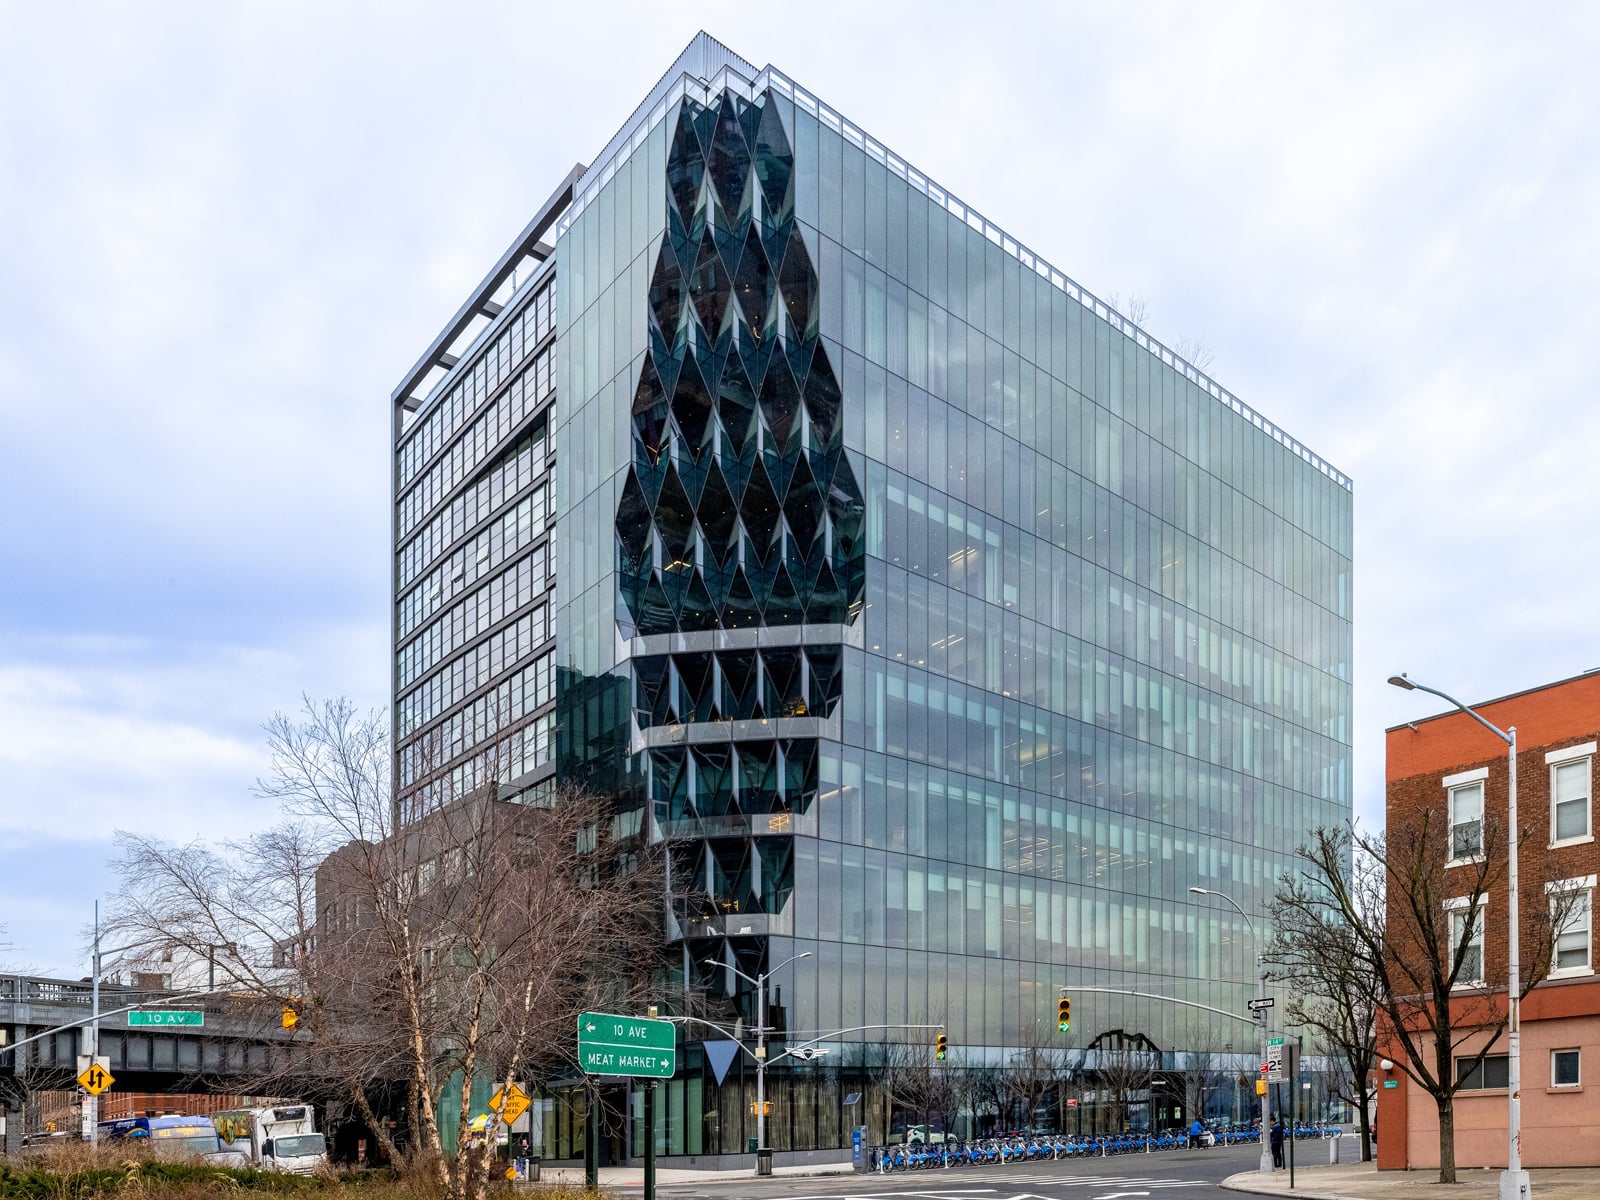
The national office vacancy rate reached 17.8 percent in August—90 basis points lower year-over-year. Manhattan continued to outperform major office markets, posting a 10.2 percent vacancy rate, the lowest among the top 25 metros and down 340 basis points year-over-year.
The national average full-service equivalent listing rate stood at $33.20 per square foot in August—38 cents lower than the previous month and up 1.7 percent year-over-year. Manhattan remained the country’s most expensive market at $72.7 per square foot, followed by San Francisco at $65.41 per square foot.
CBD pipeline contracts
The national under-construction pipeline comprised 32.4 million square feet as of August, representing 0.5 percent of total stock. Just 2.7 million square feet were underway in central business districts, or 0.2 percent of stock, marking a 61.3 percent year-over-year decline. By contrast, urban areas had 17.2 million square feet underway, while the suburban pipeline included 12.4 million square feet.
The slowdown comes as CBD properties continue to face valuation pressure. Since 2024, 73 percent of CBD buildings with comparable previous sale prices traded at a discount—compared to 48 percent of urban properties and 42 percent of suburban office assets. AI adoption, long-term space needs and uncertain economic conditions will continue to weigh on demand for large office towers in city centers.
Among the top 25 U.S. office markets, Manhattan had 3.8 million square feet underway, followed by Boston (3.6 million square feet) and Dallas (3 million square feet).
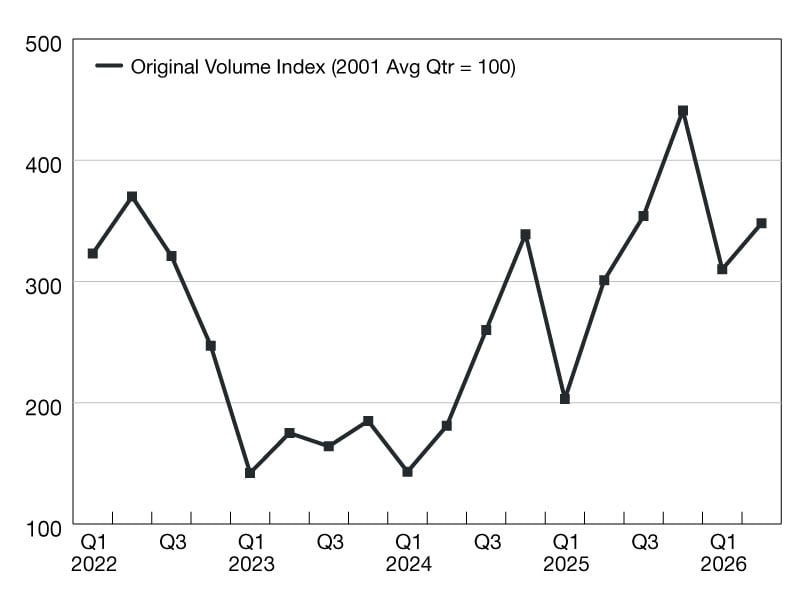
Investment activity totaled $42.7 billion across 1,850 transactions through August, with office properties selling at an average of $205 per square foot. Manhattan led for dollar volume with $5.2 billion, followed by the Bay Area at $3.4 billion.
Atlanta stood out among markets with pricing improvements, with properties selling at $158 per square foot in 2026 following three consecutive years of declines. Despite the increase, prices remained 32.8 percent below the 2022 peak of $235 per square foot and 7.1 percent below the metro’s 2019 levels.
You must be logged in to post a comment.