NYU WIRE Special Report: Follow the Money
Is there anything the robust CRE credit market can't handle?
Today’s highly liquid commercial real estate market is likely to help borrowers weather higher rates and the onslaught of loan maturities.
Loan originations rose 16 percent in the second quarter year over year and 12 percent over the first quarter, according to the Mortgage Bankers Association.
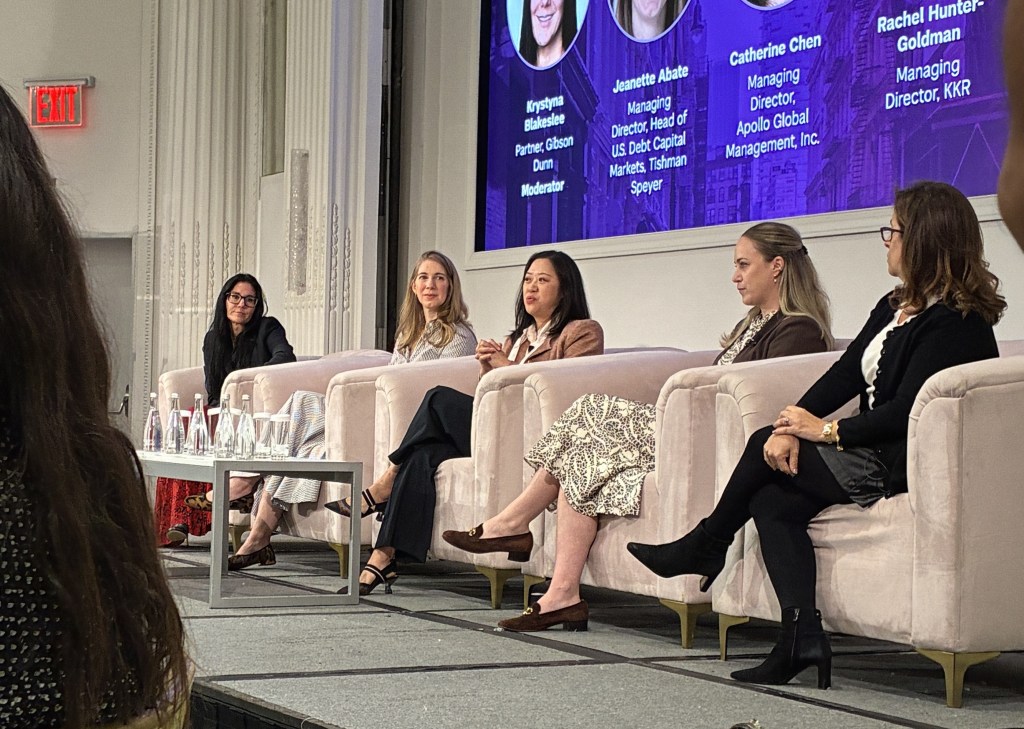
“There is a ton of capital to put to work, and everyone is active,” said KKR Managing Director Rachel Hunter-Goldman during the finance panel at NYU’s 9th National Symposium of Women in Real Estate.
Banks have fully returned as direct and indirect lenders, and CMBS issuance is up significantly, particulary for single-asset single borrower transactions, Hunter-Goldman noted. Alternative lenders are also fully engaged and have emerged as “all-weather lenders.” Only life insurance company lenders, which have a preference for fixed-rate lending in a market, saw a marked decrease in the second quarter.
READ ALSO: Is the Fed the Long Bond’s Worst Enemy?
“It’s a great time to be a borrower,” said fellow panelist Jeannette Abate, managing director & head of U.S. debt markets for Tishman-Speyer, who noted that 25 percent of SASB CMBS transactions are now office—and not just high-profile New York City office. Her firm recently secured a $340 million CMBS loan to refinance The Franklin Chicago office tower.
The panelists traced the influx of debt capital to a “major change” in the investor universe. More private investors, including high-net-worth invididuals, have turned to real estate credit for diversity, the relative value, a resetting of real estate values and improving fundamentals.
And with 60 to 70 percent of loans today being floating rate, the increase in the 10-year Treasury, which now sits at 5.3 percent, has so far not had a big impact on real estate credit spreads, with the exception of high-dollar bridge lenders perhaps being more hesitant, according to Brett Rosenberg, senior managing director of JLL Capital Markets.
Where is capital going?
While office loans are getting more attention these days, multifamily and industrial coninue to be the preferred property types. Rosenberg said JLL has seen a lot of competition and deal flow on the multifamily side. It is tracking 300 separate lenders quoting multifamily vs. 200 lenders quoting industrial and retail and 100 quoting office.
There has also been a significant rise in retail and even hospitality lending compared to a few years ago, said Catherine Chen, managing director of Apollo Global Management.
But it is the big debt funds like Apollo and a handful of other “creative financing” lenders that have helped expand the boundaries of real estate lending beyond the four or five main property types, Chen said. Apollo will lend on construction, seniors housing, parking facilities, data centers, net lease and more.
“The pie is growing” in terms of loan products and asset types, she said, as the capital markets look to grow its footprint in real estate.
The wall of maturities
In 2026, $878 million of loans will mature, and $652 billion will mature next year. Rosenberg said the “wall of maturities” is real, but a functioning capital markets with a lot of tools in its toolkit should be abe to work through most situations. Recent price disovery will also help.
“There are more rational borrowers and lenders who are finally realizing the value of their assets,” she said.
Borrower beware
While the CRE debt markets are able to manage a variety of financing needs today and pricing is competitive, the panelists emphasized the importance of relationships and structure. Chen cautioned borrowers to look beyond the sticker price to “follow the money:” Who are the lenders involved and what are their objectives for the loan?
The panel was moderated by Gibson Dunn Partner Krystyna Blakeslee.
You must be logged in to post a comment.