Is Grocery-Anchored Retail Worth the Premium?
Store performance, lease provisions and replacement costs determine how much protection investors are actually buying.
Grocery-anchored retail has become one of the most competitive corners of the investment market. In JLL’s 2026 retail investors survey, 81 percent of respondents included grocery-anchored centers in their investment plans, while 64 percent intended to ramp up their retail acquisitions this year.
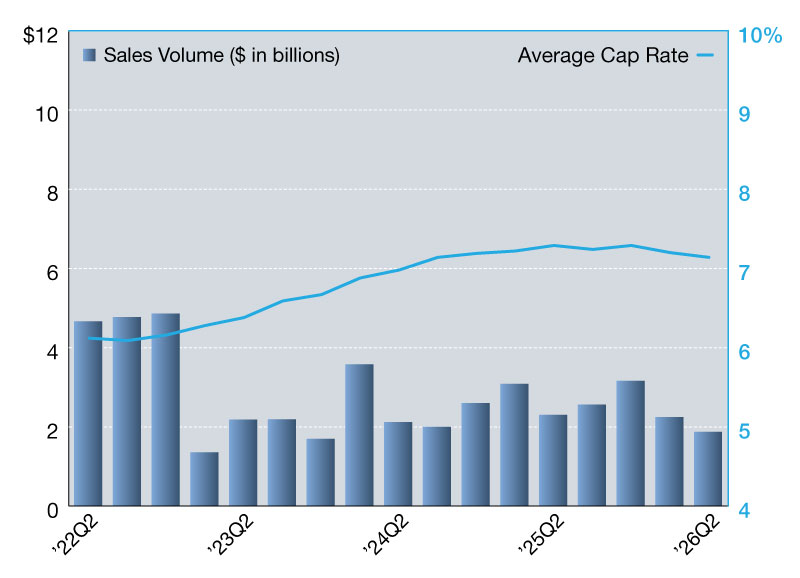
Additionally, the firm’s Grocery Tracker found that transaction volume for this property type in 2025 was nearly $11 billion, up 42 percent year-over-year, with cap rates averaging 6.7 percent at year-end, 40 basis points below their 2023 cyclical peak.
Limited construction is reinforcing the competition. National retail vacancy stood at 6 percent in the second quarter of 2026, when just 2.3 million square feet of new retail space was delivered across the country, according to Cushman & Wakefield. Asking rents increased 2.2 percent year-over-year to $25.65 per square foot.
READ ALSO: When the Real Estate’s Better Than the Rent Roll
All these conditions support the sector’s appeal, but the grocery-anchored label doesn’t make every center equally defensive. Consumer preferences are splitting traffic among traditional, value-oriented and fresh-format grocers, and individual stores can perform differently even within the same chain. JLL’s Grocery Tracker points to an increasingly important distinction: Having a grocery anchor and having the right grocery anchor are different investment propositions.
For retail buyers paying a premium for stability, the underwriting extends from the store’s competitive position to the lease provisions governing its departure and the options available if it leaves.
The store has to earn the premium
Buyer demand exceeds the inventory available for sale, contributing to meaningful valuation increases over the past year, according to Jim Hamilton, senior managing director with JLL Capital Markets. However, even at higher pricing, most grocery-anchored retail assets continue to trade below replacement cost. But that doesn’t resolve the question behind the premium: How well is the grocery anchor performing and can it keep drawing shoppers to the center?
Many grocers report store sales, allowing investors to compare rent with sales when assessing occupancy costs, Hamilton noted. Those figures become more informative when considered alongside the store’s competitive position, access, visibility and alignment with the operator’s current prototype. The merchandise mix also needs to suit the surrounding customer base.
For DLC Management Corp., a commercial real estate company that owns, operates and manages open-air shopping centers nationally, location and the grocer’s standing within its market are central to that assessment.
“Retail real estate, especially grocery-anchored real estate, is still local,” said COO Chris Ressa.
A recognizable banner can obscure weak sales trends, a declining competitive position or traffic that trails nearby grocery-anchored centers. So DLC also examines whether the operator is investing in the location: completing or scheduling remodels, maintaining the store and keeping it well stocked.
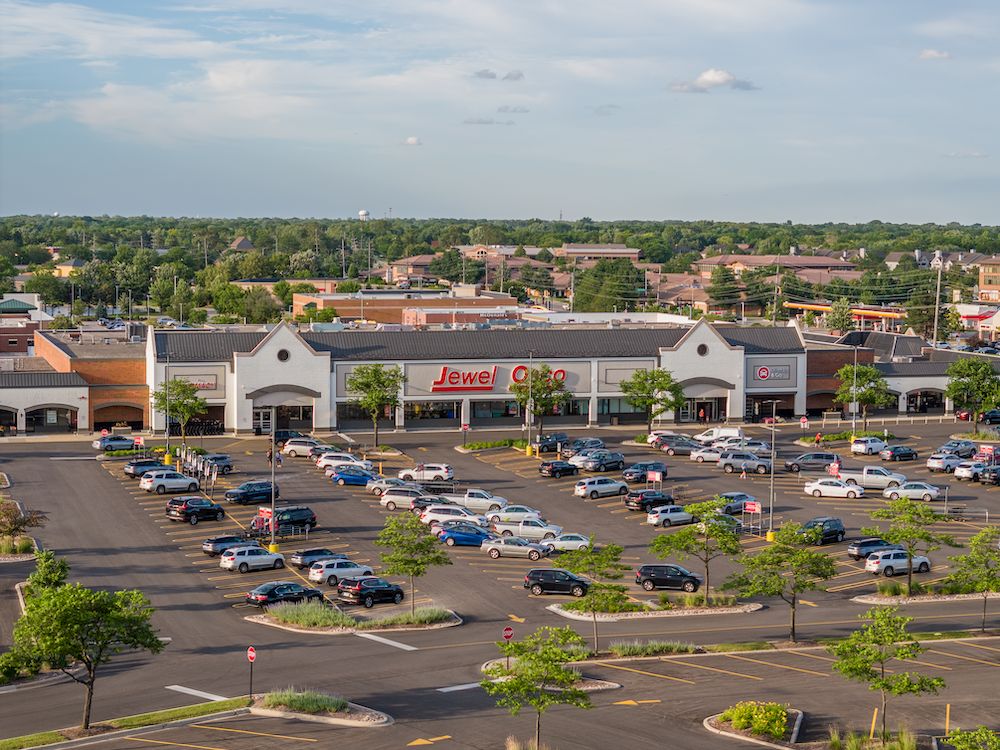
The company’s late-2024 acquisition of Danada Square West in Wheaton, Ill., illustrates that approach. DLC purchased the 314,819-square-foot shopping center for $61.7 million, in a joint venture with Crow Holdings Capital and Temerity Strategic Partners. Jewel-Osco had anchored the property since it opened in 1988. The grocer’s Chicago-market position, the individual store’s performance and its long tenure all reinforced DLC’s assessment of the location.
The anchor’s contribution also extends beyond its own rent. At Brixmor, a REIT that owns and operates close to 350 open-air shopping centers across 29 states, a grocer’s recurring traffic is part of the leasing proposition for the whole property.
“The grocer typically sets the tone for the entire property,” said Matthew Ryan, executive vice president of National Property Operations & South president at Brixmor Property Group.
Restaurants, service providers, health and wellness businesses and complementary retailers can turn those grocery visits intro additional reasons to use the center throughout the week. Ryan sees that mix supporting neighborhood tenants’ sales, leasing velocity and retention. The premium rests partly on those benefits reaching beyond the supermarket’s walls.
The lease determines how far the risk spreads
That dependence on anchor traffic makes the lease review consequential. Grocery leases often run 10 to 20 years with predetermined rent structures, providing owners with long-term income visibility, Hamilton said. Their duration, however, must be weighed against provisions that can alter an owner’s exposure.
Sales-based termination rights can affect the expected income stream. Co-tenancy clauses elsewhere in the center may create further rent or termination consequences if an anchor closes, while other restrictions can limit replacement options.
Brixmor examines those provisions before an acquisition, alongside the physical and financial implications of recovering the box. It’s review includes potential downtime, the condition in which the space would be returned and how readily it could accommodate another user, according to Ryan.
The downside therefore extends beyond losing the grocer’s rent. An anchor departure can weaken the traffic supporting small-shop tenants while restrictions complicate efforts to restore it. A center’s ability to absorb that disruption depends on both the documents and the demand for its space.
Replacing the traffic, not just the tenant
Finding another occupant is only part of the response. The replacement must fit the trade area and give shoppers a reason to return.
At Bennetts Mills Plaza in Jackson, N.J., Brixmor reassessed that demand after the grocery anchor announced its closure in early 2024. The company evaluated the customer base, competitive landscape and longer-term market needs before concluding that grocery remained the right use for the space. It selected regional kosher grocer Gourmet Glatt, whose roughly 67,000-square-foot supermarket opened in January 2026.
Ryan said the concept aligned with the surrounding community and preserved the daily-needs shopping trips supporting the broader property. The decision centered on which operator could serve the market rather than simply which tenant could occupy the box.
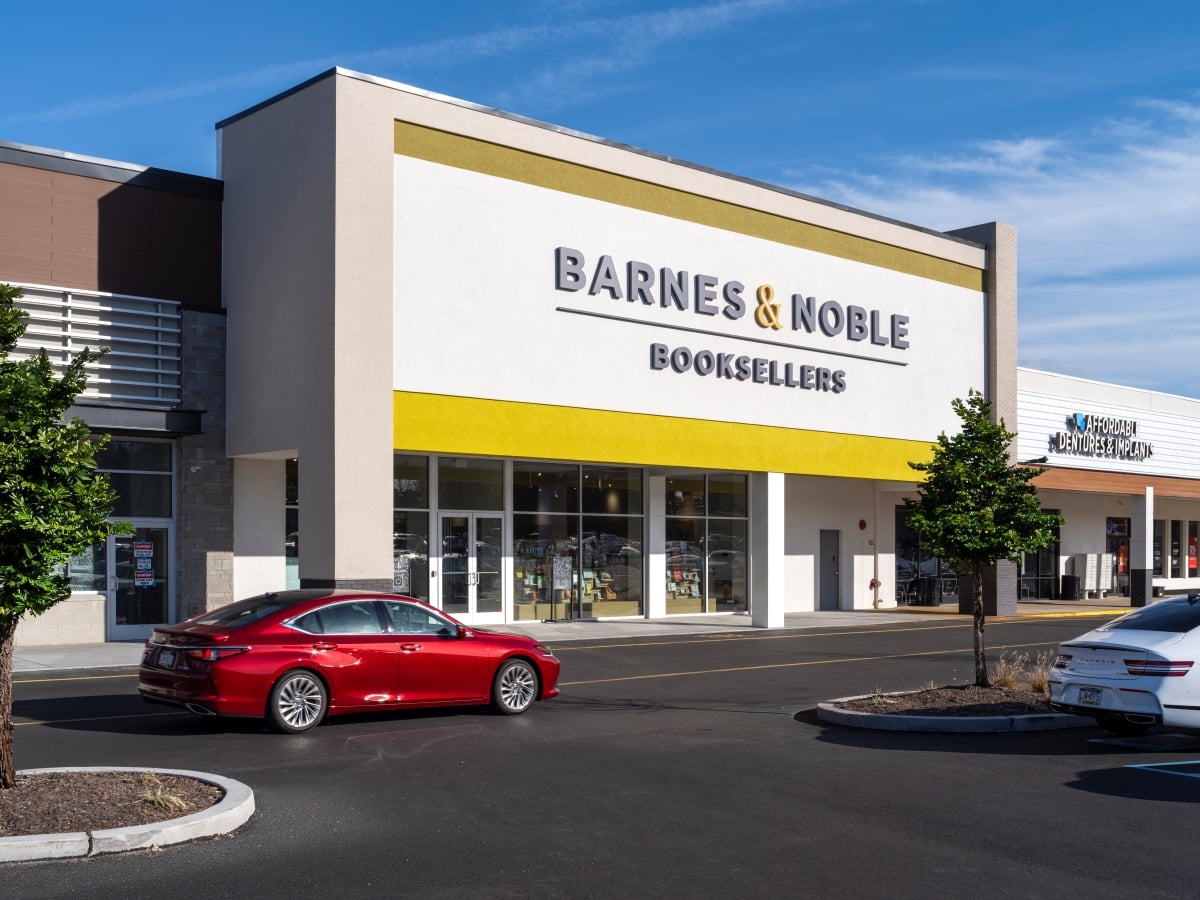
Barn Plaza in Doylestown, Pa., demonstrates a different route: using non-grocery vacancies to introduce a supermarket and reshape the center’s tenant mix. The relocation of Marshalls and HomeGoods created space for Bucks County’s first Whole Foods Market, which Brixmor incorporated into a redevelopment that also brought in Barnes & Noble and new restaurant space.
READ ALSO: Why Retail Is Shining and Office Is Thawing
The first phase was completed in the third quarter of 2025 at a net project cost of $14.6 million and generated a 9 percent incremental NOI yield, according to Brixmor. Small-shop occupancy increased from 84 percent before the reinvestment to 100 percent. The company is now pursuing another phase that replaces a former movie theater with new multi-tenant buildings.
These projects illustrate different investment decisions. Bennetts Mills retained grocery as the anchor use but changed the operator to reflect local demand, while Barn Plaza required a broader capital investment to establish a new merchandising mix. Neither outcome followed automatically from putting a grocery name on the property.
And as more capital continues to compete for limited inventory, the risk is paying for stability that the individual asset has yet to demonstrate. A strong store, supportive lease terms and credible replacement options can justify confidence, but the grocery-anchored destination alone can’t establish how durable the income will be or what restoring it might cost.
You must be logged in to post a comment.