RMR Group-Managed REIT Receives $2B Deal Proposal
The offer is for a hotel portfolio encompassing more than 21,000 keys.
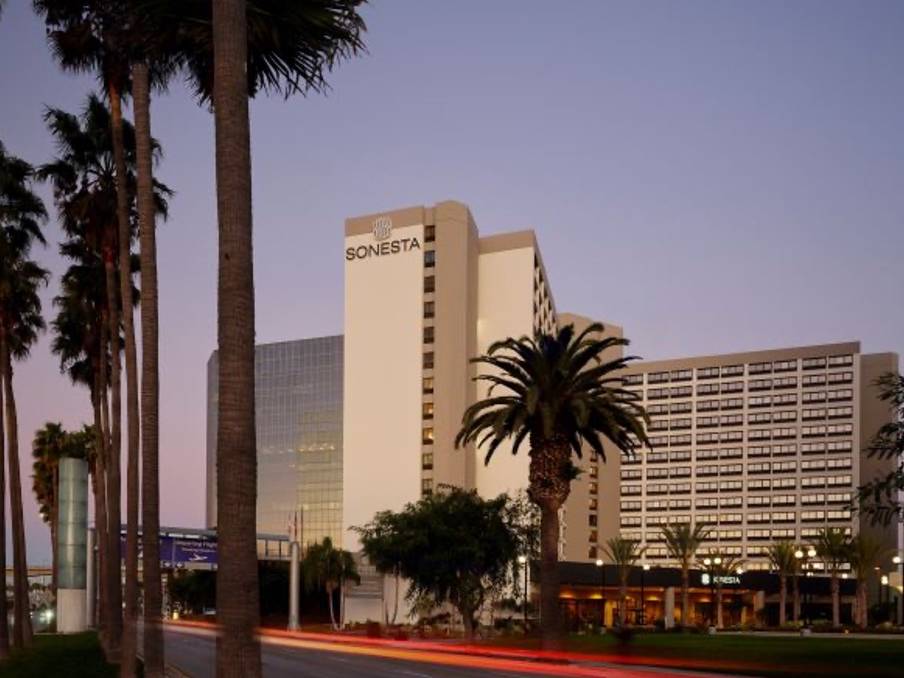
TKO has submitted an offer to acquire the hospitality portfolio of The RMR Group-managed Service Properties Trust for $2 billion, which, as of June, included 93 hotels totaling 21,110 keys.
The proposed purchase price exceeds SVC’s entire current public market capitalization. The REIT traded for $6.49 per share on Oct. 6, marking a decline of more than 50 percent across the trailing 12-month period.
SVC’s collection is spread across 31 U.S. states and D.C., as well as Ontario, Canada, and San Juan, Puerto Rico. Most hotels are in urban or high-density suburban locations proximate to major demand generators, including airports, medical or education facilities, in addition to major tourist attractions.
READ ALSO: Largest Commercial Real Estate Owners
SVC invested $9.7 billion across hospitality and service-focused retail net lease properties. The divestment of the company’s hotels would allow SVC to retire more than 40 percent of its outstanding indebtedness, while retaining its retail platform, according to TKO’s acquisition proposal.
Another giant hospitality deal began to take form in May when Fertitta Entertainment entered into an agreement to acquire Caesars Entertainment for a total of $17.6 billion, including assuming $11.9 billion in outstanding debt. Caesars shareholders approved the purchase last month. The company owned and operated 52 resorts and casinos across 18 U.S. states and Ontario.
Also last month, the largest-ever sale of a nongaming U.S. resort closed when Ryman Hospitality Properties, a lodging REIT, purchased Grande Lakes Orlando for nearly $1.4 billion. Trinity Investments agreed to sell the asset, which comprises two hotels totaling 1,592 keys, in August.
Hotel investment mends, yet financing environment shifts
The U.S. hospitality market entered the second half of the year with improving occupancy, stronger revenue growth and greater transaction momentum, including a 15 percent increase in deal velocity during the year ended in June, according to a Marcus & Millichap outlook.
However, financing prospects continue to pose headwinds as both the Treasury yield and Fed reserve benchmark ticked up, creating an environment where well-capitalized investors are able to buy with lower leverage, potentially having the upper hand when competing with other entities relying on softer interest rates.

You must be logged in to post a comment.